
Last Updated on: September 23, 2026 by Carlos P. Barry
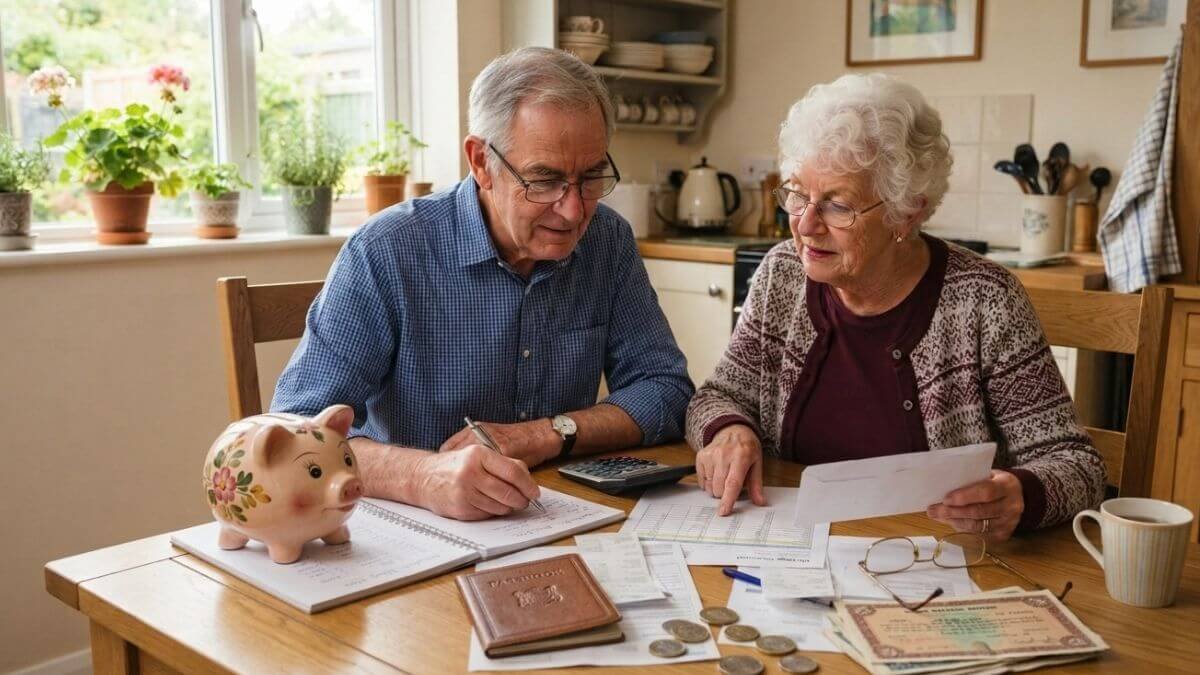
Retirement can be an exciting new chapter, but managing money on a fixed or limited income can also require careful planning. Frugal Living Tips for seniors can help retirees make the most of their income without giving up the activities, relationships, and experiences they enjoy. Frugal living does not mean giving up everything you enjoy. Instead, it means being intentional about where your money goes and finding practical ways to reduce unnecessary costs.
For seniors and retirees, small changes can make a meaningful difference over time. Reviewing recurring bills, planning meals, comparing insurance and prescription costs, using community resources, and taking advantage of available discounts can all help stretch retirement income further.
Main fact is to focus on the expenses that matter most while preserving the day to day works, engagements, relationships, and experiences that make retirement absolutely enjoyable. The following 40 Frugal Living Tips for seniors can help you identify opportunities to save without turning retirement into a constant exercise in cutting costs.
Financial Information Disclaimer: This article provides general financial information for educational purposes only. It is not personalized financial, investment, tax, legal, insurance, or retirement advice. Financial decisions depend on your income, assets, expenses, health, location, family circumstances, eligibility for government programs, and other factors. Information about Social Security, Medicare, taxes, insurance, retirement accounts, loans, and financial products can change over time. Before making a significant financial decision, consider reviewing current information from the appropriate government agency and consulting a qualified professional who understands your circumstances.
How Can Seniors Save Money in Retirement?
The most effective frugal strategies for seniors generally fall into seven areas:
- Manage your budget: Know how much money comes in and where it goes each month.
- Reduce housing and utility costs: Look for ways to lower energy bills, insurance costs, subscriptions, and other recurring expenses.
- Spend strategically on food: Planning of regular food cost, seasonal shopping, and reducing food waste can lower grocery costs.
- Manage healthcare expenses: Compare prescription prices, review coverage, and ask about lower-cost options when appropriate.
- Reduce transportation costs: Combine errands, use public transportation if possible and investigate senior transportation programs.
- Enjoy low-cost activities: Libraries, community programs, senior discounts, and free events can provide entertainment without a large budget.
- Review your retirement plan: Revisit taxes, insurance, beneficiaries, fees, and your overall budget regularly.
You can also explore our retirement jobs and low-stress work ideas if earning additional income is appropriate for your situation.
40 Frugal Living Tips for Seniors:
# Budgeting & Money Management

1. Create a retirement budget
Start with a realistic picture of your monthly income and essential expenses. Include housing, utilities, food, transportation, healthcare, insurance, debt payments, entertainment, and other regular costs. A clear budget makes it easier to see how much you can comfortably spend on nonessential items.
2. Track monthly spending
A budget is more useful when you know whether your actual spending matches it. Review bank and credit-card statements regularly and keep a simple record of purchases. You may discover recurring expenses that you had forgotten about. This could be an way through which you can erase such cost from your spending list.
3. Separate needs from wants
Before making a purchase, ask whether it is necessary, useful, or simply something you would like to have. This does not mean eliminating every enjoyable purchase. It means making room for the things you value most.
4. Build an emergency fund
Unexpected home repairs, medical expenses, or transportation problems can disrupt a retirement budget. Keep an accessible savings reserve that fits your circumstances. The appropriate amount depends on your income, expenses, insurance, health needs, and other resources.
5. Review recurring expenses
Recurring charges can quietly consume a significant portion of a monthly budget. Review phone plans, memberships, streaming services, insurance premiums, software, and other automatic payments at least once a year.
6. Avoid unnecessary debt
High-interest debt can make a fixed income harder to manage. Focus on avoiding new debt that does not provide meaningful value, and create a realistic repayment strategy for existing balances.
Be cautious about taking on new loans simply to cover everyday spending. If debt is difficult to manage, consider getting advice from a qualified financial or credit professional before making major changes.
7. Compare financial fees
Banking, investment, account-management, and transaction fees can add up over time. Review the fees you are paying and understand what you receive in return. Before switching accounts or investments, consider tax consequences, withdrawal rules, and other costs.
# Housing & Utilities

8. Reduce energy use
Simple changes such as turning off unused lights, adjusting the thermostat, improving insulation, and using energy-efficient appliances may help reduce utility costs. Focus first on changes that are practical for your home and climate.
9. Compare insurance costs
Review your home, auto, health, and other insurance coverage periodically. Compare available options from the list while making sure you are not sacrificing important coverage simply to obtain a lower premium.
10. Consider downsizing
If your home is larger than you need, downsizing may reduce certain housing, maintenance, utility, and property-related costs. However, moving also has expenses, so compare the total financial and lifestyle impact before making a decision.
11. Negotiate service bills
For some services, it may be possible to ask about promotional rates, lower-cost plans, or discounts. This can apply to internet, phone, cable, and other services. Before accepting a new offer, check the contract terms and the price after any introductory period.
12. Review subscriptions
Make a list of every subscription you pay for. Cancel services you rarely use and consider lower-cost alternatives for those you want to keep.
# Food & Groceries

13. Meal plan
Planning meals before shopping can reduce impulse purchases and make it easier to use the food you already have. A simple weekly plan can be enough.
14. Buy seasonal food
Seasonal fruits and vegetables may be less expensive and can provide variety in your meals. Compare prices rather than assuming that every seasonal item will always be the cheapest option. Such seasonal food items are healthy as well.
15. Use grocery loyalty programs
If you regularly shop at a particular store, its loyalty program may provide access to discounts or special offers. Read the terms and avoid buying unnecessary items simply because they are promoted as a deal.
16. Cook larger batches
Preparing larger portions can save time and make it easier to have inexpensive meals available later. Freeze appropriate portions if you can use them before their quality declines.
17. Reduce food waste
Check your refrigerator and pantry before shopping. Store food properly, use older items first, and freeze foods that you will not use soon. Reducing waste means getting more value from groceries you have already purchased.
# Healthcare
18. Compare prescription costs
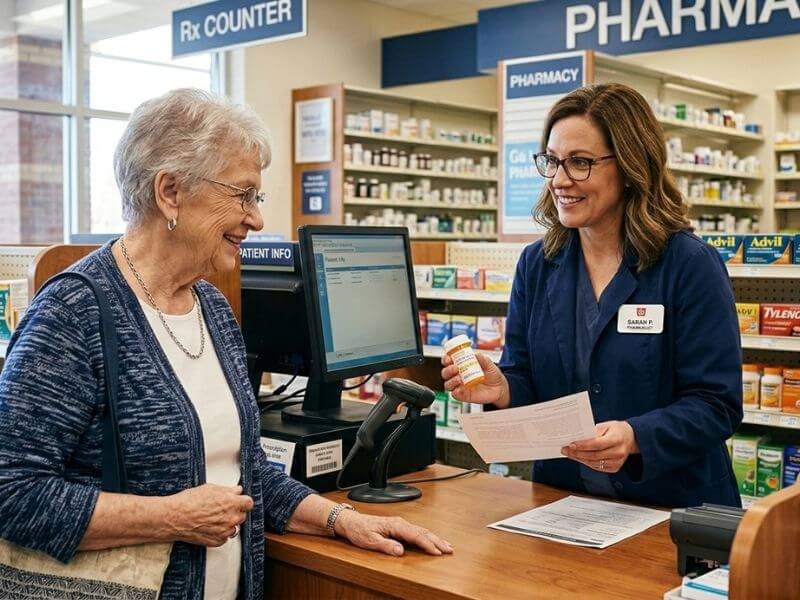
Prescription prices can vary between pharmacies, plans, and purchasing options. Ask your healthcare provider or pharmacist whether there are lower-cost alternatives that are appropriate for you. Medicare also recommends comparing drug plans and asking about generic or lower-cost alternatives when available.
19. Review insurance coverage
Healthcare needs can change over time, so review your coverage during the appropriate enrollment or renewal periods. Understand premiums, deductibles, copayments, out-of-pocket costs, networks, and prescription coverage before making changes.
20. Use preventive care
Keep up with preventive care and recommended screenings that are appropriate for your age and circumstances. The goal is not to promise that preventive care will eliminate future medical costs, but to make informed use of healthcare services that may help identify problems earlier.
21. Ask about generic medications
When you receive a prescription, ask your doctor or pharmacist whether a generic medication is an appropriate alternative. Generic drugs can sometimes cost less, but the right choice depends on the medication and your individual circumstances.
22. Look for legitimate assistance programs
Depending on where you live and your circumstances, you may qualify for assistance with prescription drugs, healthcare, food, utilities, or other essential expenses. Use government agencies, established nonprofits, and official program websites when checking eligibility.
Avoid giving personal or financial information to an organization simply because it promises unusually large savings.
# Transportation

23. Use public transportation
When practical and accessible, buses, trains, and other public transportation can reduce fuel, parking, maintenance, and other vehicle-related expenses.
24. Combine errands
Instead of making several separate trips, group errands that are located near one another. This can save fuel and time while making your weekly schedule simpler.
25. Look for senior transportation programs
Some communities offer reduced-fare transportation, paratransit, community shuttles, volunteer transportation, or other services for older adults. Contact your local government or senior services organization to learn what is available in your area.
26. Review car ownership costs
Owning a car involves more than the monthly payment. Consider insurance, fuel, maintenance, registration, repairs, parking, and depreciation. If you rarely drive, compare the total cost of ownership with practical alternatives before replacing your vehicle.
# Entertainment & Lifestyle

27. Use libraries
A library card can provide access to books, magazines, movies, digital resources, classes, events, and other low-cost or free activities. Availability varies by library.
28. Look for senior discounts
Ask businesses, attractions, restaurants, transportation providers, and other organizations whether they offer senior discounts. Some discounts are available only on specific days or at certain times.
For more ideas, see our guide to senior-friendly activities and lifestyle ideas.
29. Use free community programs
Check local community centers, parks, libraries, museums, senior centers, and nonprofit organizations for free or inexpensive programs. These may include classes, social events, educational programs, exercise opportunities, and entertainment.
30. Travel during less expensive periods
If travel is part of your retirement plans, consider comparing prices during shoulder seasons or other less busy periods. Look at the total cost of transportation, lodging, meals, activities, and travel insurance rather than focusing only on the advertised room or ticket price.
You can also explore our guides to senior travel and vacation ideas when planning a trip.
# Shopping
31. Compare prices
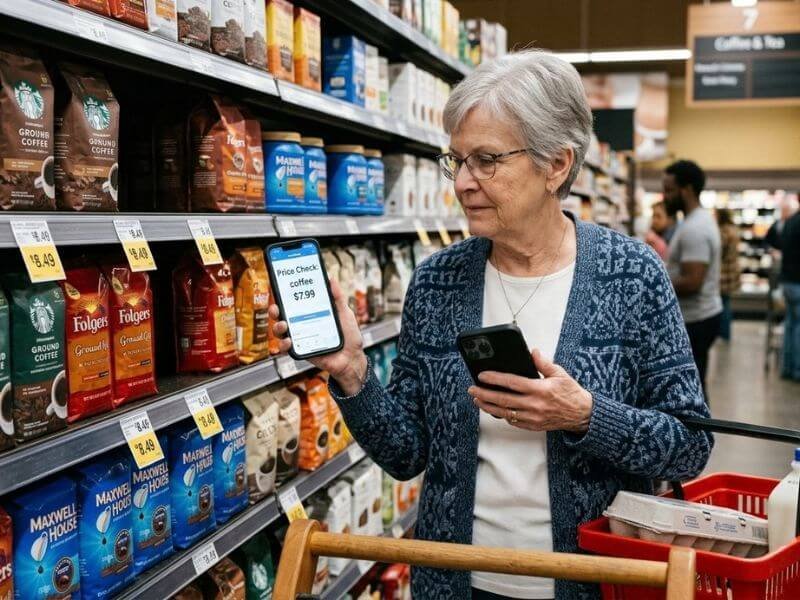
Do not assume the first price you see is the best one. Compare retailers, online stores, local businesses, and available promotions. Also check shipping costs, return policies, warranties, and other fees before deciding.
32. Buy quality instead of quantity
A cheaper product is not always the least expensive choice over time. For items you expect to use frequently, consider durability, maintenance, warranty coverage, and expected lifespan as well as the initial price.
33. Use coupons carefully
Coupons can reduce the price of items you already planned to buy. However, a discount is not a saving if it encourages you to purchase something you do not need.
34. Consider secondhand purchases
Clothing, furniture, books, tools, and some household goods can often be purchased secondhand. Check the condition, safety, functionality, and return policy before buying.
# Retirement Planning

35. Review beneficiaries
Review beneficiary designations on retirement accounts, insurance policies, and other financial accounts after major life changes. Beneficiary rules can vary by account and location, so seek professional guidance when necessary.
36. Review insurance annually
Your insurance needs may change as your finances, health, home, vehicle use, or family circumstances change. An annual review can help you identify coverage you no longer need as well as gaps that should be addressed.
37. Understand taxes on retirement income
Retirement income is not necessarily tax-free. Depending on your country and the type of income, pensions, retirement-account withdrawals, annuities, investment income, and government benefits can have different tax treatment. In the United States, for example, the IRS provides specific guidance on taxation of retirement distributions and Social Security benefits.
Before making a large withdrawal or changing your income strategy, consider speaking with a qualified tax professional.
38. Be cautious with financial offers
Be skeptical of unsolicited investment opportunities, guaranteed-return claims, urgent sales pitches, and requests for personal financial information. Take time to verify the company, understand the product, and seek independent advice when appropriate.
39. Avoid unnecessary financial products
Not every annuity, investment, insurance product, or financial service is appropriate for every retiree. Understand fees, risks, liquidity restrictions, surrender charges, taxes, and potential benefits before purchasing a product.
40. Review your budget every year
Your retirement budget should evolve as your circumstances change. Review income, housing costs, healthcare expenses, insurance, taxes, subscriptions, debt, and discretionary spending at least annually.
A yearly review can also help you identify expenses that have increased and decide whether adjustments are necessary.
A note about reverse mortgages: A reverse mortgage may be relevant in some circumstances, but it is not a universal solution for retirement expenses. If you are considering one, understand the costs, repayment requirements, effect on other financial goals, and potential impact on heirs and benefits. Consider independent advice and appropriate counseling before making a decision.
How Much Should a Retiree Keep in an Emergency Fund?
There is no specific boundary of emergency-fund amount that works for every retiree. A common starting point is to keep several months of essential expenses in accessible savings, but the right amount depends on your income stability, healthcare needs, insurance coverage, housing situation, debt, and other financial resources.

Retirees with predictable income and strong insurance coverage may have different cash needs from someone facing irregular expenses or substantial home and healthcare costs.
The important point is to keep emergency savings accessible and separate from money intended for long-term investing. Consider discussing the appropriate reserve with a qualified financial professional if you are unsure.
Frequently Asked Questions
How can seniors live frugally on a fixed income?
Start by identifying essential expenses and tracking where your money goes each month. Then focus on recurring costs such as housing, utilities, insurance, transportation, subscriptions, and groceries. Use legitimate discounts and community resources where available, and review your budget regularly.
The goal is not to eliminate everything enjoyable. A sustainable frugal lifestyle should leave room for the activities and experiences that matter to you.
What is the easiest way for retirees to save money?
The easiest starting point is often to review recurring expenses. Cancel unused subscriptions, compare service plans, review insurance costs, and look for fees you may be able to reduce.
Automating a small transfer to savings can also help if your income and budget allow it.
How can seniors reduce monthly expenses?
Begin with the largest flexible expenses rather than trying to cut dozens of tiny purchases. Housing, transportation, insurance, utilities, food, debt payments, and recurring subscriptions can all be worth reviewing.
Make changes gradually and prioritize reductions that do not negatively affect your safety or essential needs.
What expenses should retirees cut first?
Start with expenses that provide little value relative to their cost. Unused subscriptions, unnecessary memberships, avoidable fees, expensive service plans, impulse purchases, and unused insurance coverage may be good places to look.
Be more cautious about cutting healthcare, appropriate insurance, nutritious food, home safety, or transportation that you genuinely need.
How much should a retiree keep in an emergency fund?
There is no universal number. A reserve covering several months of essential expenses is a common starting point, but retirees should consider their income, healthcare needs, insurance, housing, debt, and access to other resources.
Keep emergency savings in an accessible account and review the amount periodically as your circumstances change.
Frugal living in retirement is less about deprivation and more about making deliberate choices with your money. You do not have to stop traveling, eating out occasionally, pursuing hobbies, or spending time with family and friends simply because you want to save.
Instead, look for areas where spending can be reduced without sacrificing what matters most to you. Just need to spend consciously to make it a habit. Track your expenses, review recurring costs, compare prices, use appropriate discounts, and revisit your retirement plan regularly.
For more ideas for enjoying retirement without overspending, explore our retirement lifestyle articles and travel guides for seniors. If earning additional income is part of your plan, our low-stress retirement job ideas may also be useful.
Written By